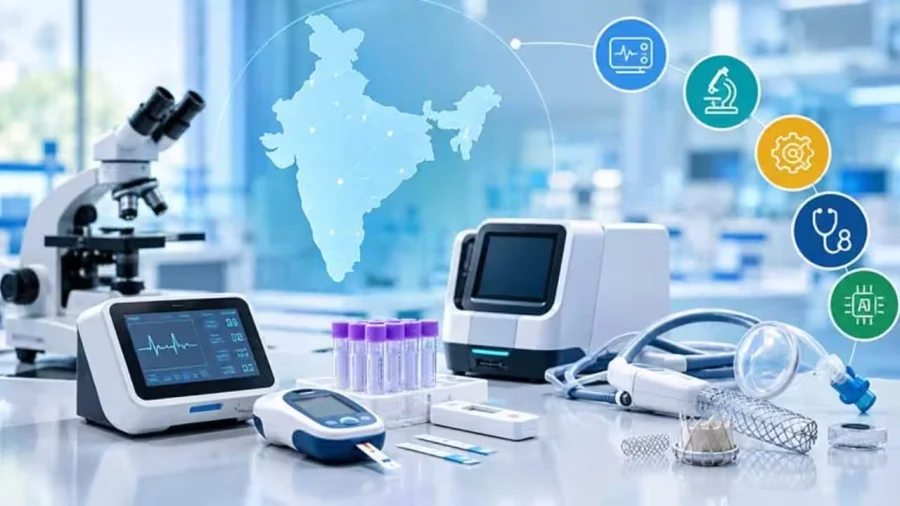
Every stent, dental implant and imaging scanner that enters an Indian hospital carries two price tags. One is printed on the invoice. The other was set years earlier, on a factory floor — usually in another country. That gap is at the centre of a policy exercise now underway at NITI Aayog, which is examining how to shift more of that manufacturing — and that pricing power — into India.
The government's public policy think tank has been consulting domestic manufacturers, government officials and technical experts from IIT Delhi and IIT Mumbai to identify what is holding the sector back. Two themes dominated: regulatory friction, and the cost disadvantage Indian firms say they carry against imported rivals.
A Consultation That Started With an Uncomfortable Question
The question running through the discussions is easy to pose and difficult to answer. If India can build world-class pharmaceuticals and assemble complex electronics, why does it remain cheaper for a hospital to import a high-end device than to buy one made a few hundred kilometres away?
That question matters because medical devices are not a niche category. The sector spans consumables such as syringes and sutures, diagnostics, implants, and capital equipment like MRI and CT machines. India has a meaningful presence in some of these segments and a thin one in others.
Where the Cost Gap Actually Comes From
Manufacturers point to scale. A domestic firm producing in smaller volumes spreads fixed costs — plant, testing, quality certification, sterilisation — over fewer units, so each device carries a heavier burden.
Component dependence is the second factor. Many Indian device makers still import critical parts, sensors, polymers and precision-machined assemblies, which means currency movement and global supply shocks land directly on their cost sheet. Regulatory compliance adds a third layer.
In the NITI Aayog discussions, these cost disadvantages were raised extensively — a signal that the economics of local production, not just the ambition of it, are now on the table.
How the Regulatory Conversation Became Central
India regulates medical devices under the Medical Devices Rules, 2017, with the Central Drugs Standard Control Organisation (CDSCO) as the apex regulator. The framework was a significant step toward formal oversight, and it brought a wide range of products under licensing for the first time.
For manufacturers, however, the compliance path involves facility audits, product testing, documentation and repeated approvals for new variants. Small and mid-sized firms argue that the same pathway designed for large multinationals can be disproportionately heavy for them.
That is the argument AiMeD has carried into the consultations: simpler regulation and financial support for local manufacturers, so that a homegrown firm is not spending its scarce capital on paperwork rather than production.
Why a Dental Chair Manufacturer's Problem Is a Patient's Problem
Import dependence does not stay inside an industry balance sheet. It travels. When a large share of high-end equipment is sourced from abroad, hospital procurement budgets are exposed to exchange rates, freight costs and global supply disruptions.
The consequences show up in familiar places — the price quoted for a scan, the cost of an implant in a tier-2 city, the speed at which a district hospital can replace a broken machine. Domestic capacity does not automatically lower prices, but it widens the options available to buyers.
There is an employment dimension too. Device manufacturing is skilled, relatively clean work — the kind of industrial base policy planners want in clusters beyond the big metros.
What the Meeting Put on the Record
The consultation brought together three sets of voices that do not always sit in the same room: companies that build devices, officials who administer the rules, and academic engineers who study how manufacturing systems scale.
The inclusion of IIT Delhi and IIT Mumbai suggests a technical strand to the exercise — questions of design capability, testing infrastructure and process engineering, rather than only tariffs and incentives. Officials have not publicly committed to any specific measure.
Reading the Silence: What Was Not Said
No draft policy, incentive structure, or implementation calendar has been made public following the consultations. That absence is itself informative. It indicates an early-stage scoping exercise rather than a decision awaiting announcement.
It also means the specifics — whether support takes the form of production-linked incentives, shared testing facilities, faster approval channels, or procurement preferences — remain genuinely undecided.
What Is Confirmed and What Is Still Unclear
Confirmed: The consultation took place; it involved domestic manufacturers, government officials and experts from IIT Delhi and IIT Mumbai; regulatory hurdles and cost disadvantages were discussed; AiMeD sought simpler regulation and financial support.
Unclear: Whether any policy measure has been agreed, what fiscal outlay might be involved, which device categories would be prioritised, and the timeline for any recommendation. Any figure or scheme circulating beyond this should be treated as unverified until officially disclosed.
Where Indian Device Makers Believe Their Edge Lies
The industry's case rests less on matching global giants at the top of the market and more on the segments where India already has depth — consumables, surgical instruments, orthopaedic and dental products, and affordable diagnostics.
In these areas, the advantage is not a single technology but a combination: existing manufacturing clusters, a large domestic hospital network that can serve as a proving ground, cost-competitive engineering talent, and a pharmaceutical ecosystem that already understands regulated production.
Whether policy can convert that combination into durable scale is the open question. Clusters tend to strengthen when testing, certification and component supply sit close together — which is exactly what fragmented, small-scale producers lack.
The Case for Patience — and the Case Against It
There is a reasonable argument for moving carefully. Medical devices are implanted in bodies. Relaxing approval standards to help domestic firms would be the wrong trade, and regulators are rightly wary of any change that could weaken safety oversight.
Incentives carry their own risks. Support schemes can end up subsidising assembly rather than genuine manufacturing, if imported components are simply put together locally. Critics of such programmes argue that without deeper component ecosystems, the value added stays modest.
Manufacturers counter that without some transitional support, the sector will keep losing ground to importers with larger scale and settled supply chains. Both positions contain something true, which is why the policy question is harder than it first looks.
A Wider Signal About India's Manufacturing Ambitions
This exercise fits a broader pattern. India has spent much of the past decade trying to move up the manufacturing value chain in sectors it once imported wholesale — electronics, solar modules, defence components, active pharmaceutical ingredients.
Medical devices belong on that list, and for a specific reason: the demand is domestic, growing, and relatively insulated from export cycles. A hospital bed in Bihar or Kerala creates the same underlying need for a stent or a syringe.
If You Run a Device Firm — or Buy From One
For manufacturers, the practical takeaway is to engage early. Policy consultations at this stage are where categories get defined and eligibility criteria take shape; firms that wait for a published scheme usually find the design already fixed.
For hospitals and procurement teams, the near-term picture does not change. Imported high-end equipment will remain the default in several categories for now. For patients, there is no reason to expect any immediate price movement — this is a policy conversation, not a market event.
What Could Happen Next
The likeliest next step is further consultation, followed by a set of recommendations that could feed into a broader government strategy on device manufacturing. Those recommendations may or may not translate into concrete schemes.
Watch for three indicators: whether a formal policy paper or task force is announced, whether testing and certification infrastructure gets specific attention, and whether any proposal addresses component supply rather than only final assembly. Each would signal how serious the follow-through is.
Our Take
India's medical device problem is not a shortage of ambition. It is a structural mismatch — a regulatory system built for safety, an industry built at small scale, and a market that rewards importers with settled supply chains.
NITI Aayog's consultations do not resolve that mismatch. But they place the right question on the table: not whether India should make its own devices, but what specifically prevents it from doing so at a competitive cost. That is a more useful conversation than another headline about self-reliance — provided it produces decisions, and not only discussion.
Frequently Asked Questions
What is NITI Aayog doing for medical device manufacturing in India?
NITI Aayog is exploring policy measures to strengthen domestic manufacturing of medical and dental devices. It has consulted domestic manufacturers, government officials and experts from IIT Delhi and IIT Mumbai to identify regulatory and cost-related obstacles. No policy has been finalised yet.
What are the main challenges facing Indian medical device manufacturers?
Two issues were discussed extensively: regulatory hurdles in the approval and compliance process, and cost disadvantages that make local production less competitive than importing. Limited scale and dependence on imported components contribute to the cost gap.
What is AiMeD asking the government for?
AiMeD, the industry body representing Indian medical device manufacturers, has sought simpler regulations and financial support for local manufacturers so they can compete more effectively against imports.
Will this make medical devices cheaper for patients?
Not immediately. The consultations are exploratory and no pricing or procurement policy has been announced. Any impact on device prices would depend on the specific measures eventually adopted and how quickly domestic capacity expands.